Often, yes. Files refresh on a cycle, so new applications, loans and repayments since the last update don’t reach the lender in time. This 3-minute read looks at what that gap hides, what it costs lenders and good borrowers, and what a real-time credit data source should be able to do.
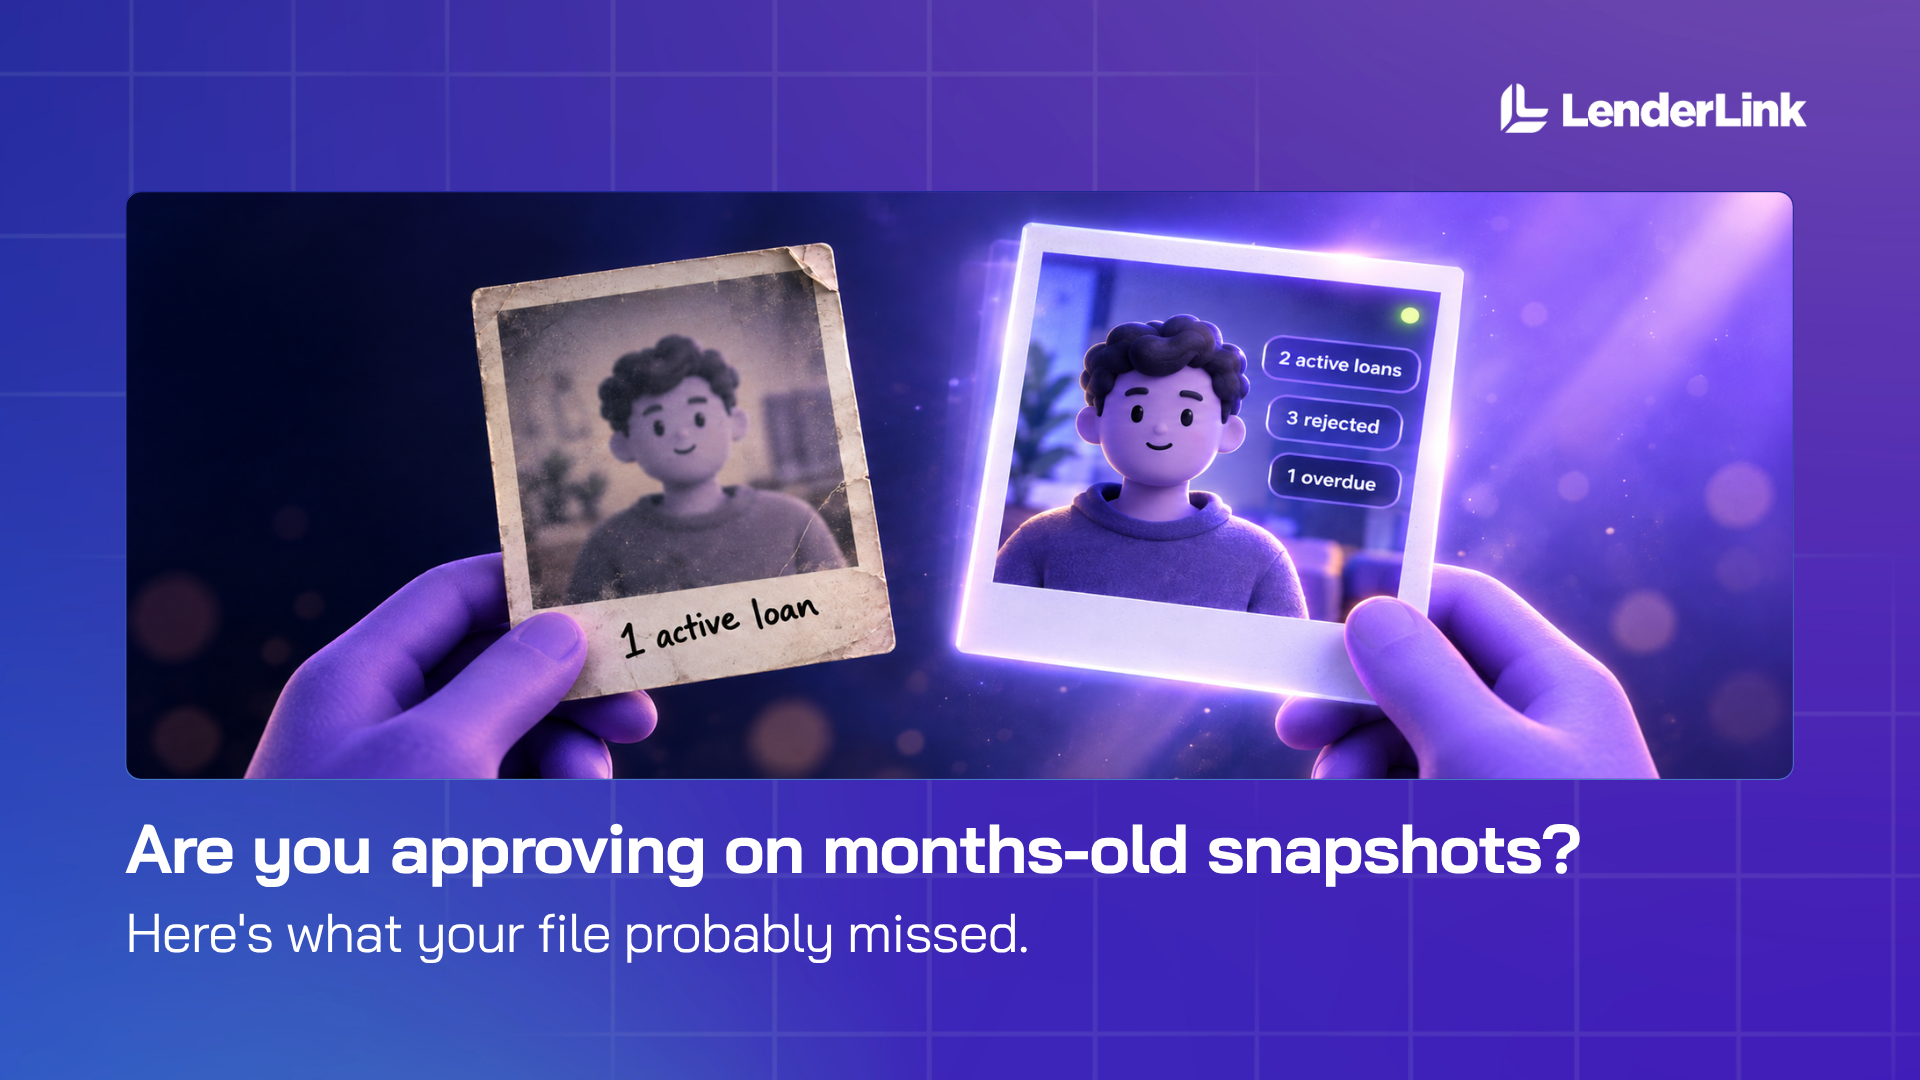
Many Philippine lenders still approve loans on credit files that are months old because the file is the record they have at the point of decision. Files refresh roughly every 30 to 45 days, so a new application or a repaid loan from last week isn’t in it yet. Real-time borrower data shows that missing stretch: new applications, new loans, and repayments since the last update.
Why does the age of a credit file matter so much?
Think about what happens after a file is updated. The borrower’s life carries on for another month or two, and the file knows nothing about it.
Christo Georgiev, our co-founder and CEO, puts the whole case in one sentence about what real-time data does:
“It captures changes in behavior of the borrower ever since the last snapshot, the last time their credit file was updated.”
This matters more in the Philippines than in markets with several consumer safety nets. Christo’s point is that behavior changes reach a bigger share of the population here, and they come more often. A household with little cushion can change how it borrows within days of one emergency, and the file won’t reflect any of it.
What does a lender miss when the file is out of date?
Take a borrower with an excellent repayment history. Last week something went wrong at home and they needed cash quickly, so they applied to several lenders at once. None of those applications have reached the file yet, so you approve someone you believe is stable. The history behind that belief is accurate. It’s just old.
This is what people mean by debt stacking, or multi-lender borrowing. Each lender sees one loan while the borrower carries several, so nobody is pricing the real risk, and the borrower is the one who ends up overindebted. With real-time visibility, the applications and new loans from the past week or two are in front of you when you decide.
What does real-time credit data change for the borrower?
The same delay works against good borrowers, and it’s easy to miss because nobody hears about a decline they never see. Suppose someone takes a loan with weekly repayments, or a term under a month, and pays it off in two weeks. That’s a clear, recent sign of reliability, and the next lender can’t see it because it happened after the last update. For a borrower with a thin file, that repaid loan could be a large part of what they have to show, and today it counts for nothing.
Sharing this kind of information in real time lets lenders price risk more accurately, and that better pricing should show up over time as lower rates and more flexible loan products.
What should a real-time credit data source be able to do?
Before you compare providers, it helps to decide what you’d hold any of them to. We’d start with four things. The data should be fresh enough to catch a change within the same week a borrower applies. It should carry good behavior as well as bad, so a loan repaid in two weeks counts for the borrower. It should run on consent, in line with the Data Privacy Act and National Privacy Commission rules. And it should sit inside your approval process, because a report that arrives after the decision doesn’t help anyone.
Where does LenderLink fit?
LenderLink operates a consent-based credit data exchange network, and we’re a CIC-recognized technology service provider. We work next to your existing bureau files.
It’s worth being precise about the mechanics, because people often assume a network like this broadcasts everything to everyone. It doesn’t. With LenderLink, lenders report hashed identifiers to the network. A record becomes identifiable only when the borrower gives consent, and then it goes only to the lender who asked about that specific borrower. Nobody gets a view into another lender’s book.
Against the four points above, that’s what we built for: current data, good and bad behavior, consent on every lookup, and a check your credit operators can run at the point of approval.
If you want to see what this looks like on your own book, start with a simple count. Take last quarter’s approved loans and find how many of those borrowers applied with another lender in the two weeks before you approved them. If you can’t answer that today, we’re happy to walk your credit team through how the check would work on your actual applications.
What does this look like in a nutshell?
Here’s the same story as a quick visual.
The setup
📸 The snapshot
A credit file is a snapshot. It updates roughly every 30 to 45 days.
The problem
🙈 What the file misses
Last week, Ana needed cash fast and applied to several lenders. None of it is in her file yet.
The lender approves on a file that is accurate about the past and silent about now.
The fix
⚡ With real-time data
Replay the same moment. This time, Ana says yes first. With the borrower’s consent, the lender can see recent applications and loans for that borrower, and only that borrower.
The upside
🌱 The good news side
Meet Ben. His file is thin. He takes a 2 week loan and repays it in full. Good behavior counts too, if the lender can see it.
Real-time credit data shows what a borrower did since the last update.
LenderLink. Consent-based credit data exchange network.